
BREAKING | October 28, 2026
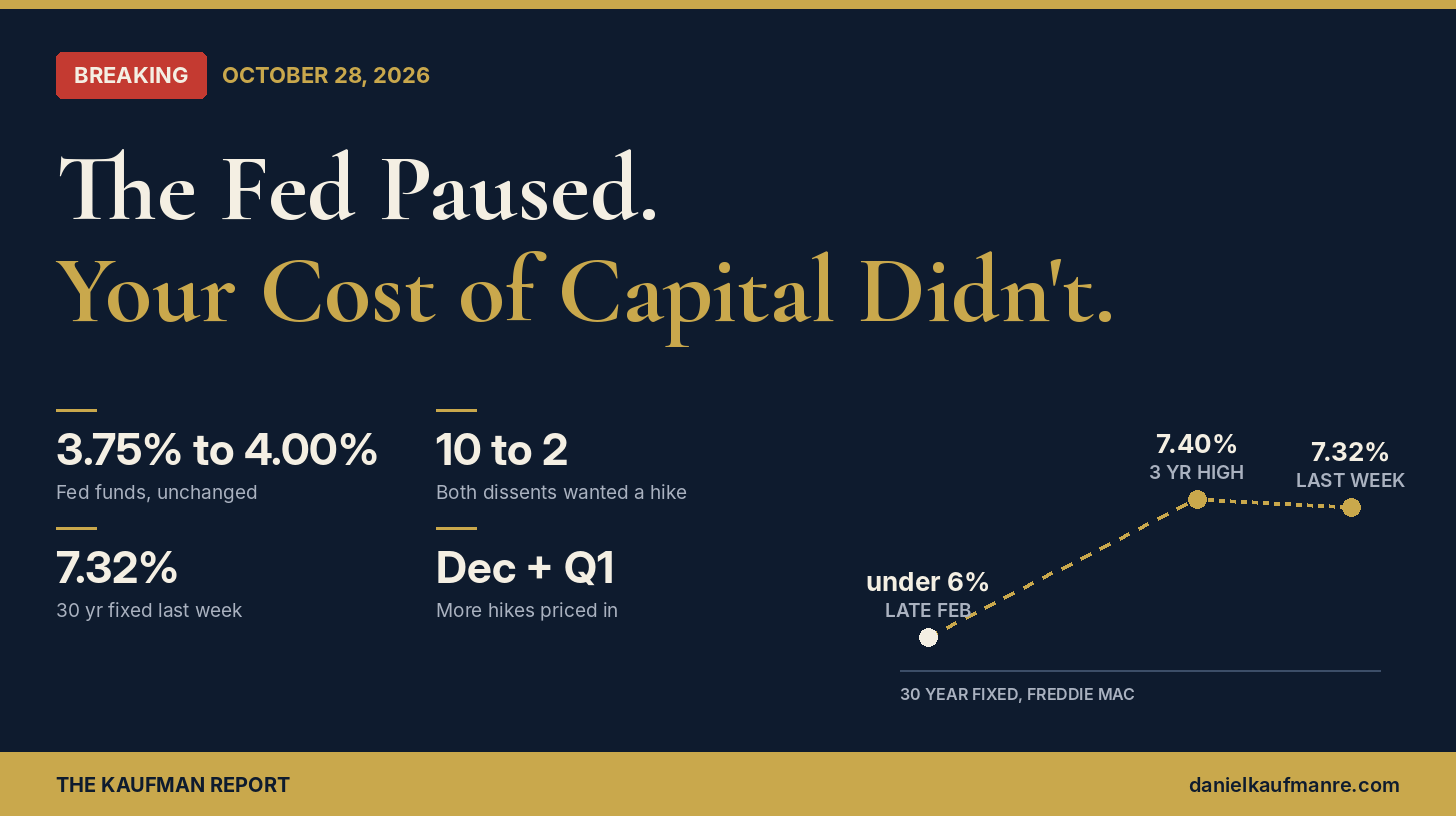
The Federal Open Market Committee left the federal funds rate unchanged this afternoon at 3.75% to 4.00%. The vote was 10 to 2, with Chair Kevin Warsh in the majority. Governor Lisa Cook and Cleveland Fed President Beth Hammack dissented, and both wanted another quarter point increase.
Read that again. The dissents were not for a cut. They were for a hike.
The numbers that matter today
-
Fed funds: 3.75% to 4.00%, unchanged
-
The vote: 10 to 2, both dissents in favor of raising rates
-
Last month: the first hike in three years
-
30 year fixed: 7.32% last week per Freddie Mac, just off a three year high of 7.40%
-
Late February: mortgage rates briefly dipped below 6%
-
Market pricing: another quarter point in December, and at least one more in the first quarter of 2027
This is a pause, not a pivot
The midterms are less than a week away. Holding steady keeps the Fed out of the headlines while voters head to the polls. That is timing, not a change in direction.
Nothing in today’s vote says inflation is beaten. Two members wanted to hike, and the market is pricing two more increases. I am underwriting as if the tightening cycle is still running, because the people setting the price of money are telling us it is.
The Fed doesn’t set your mortgage rate. The 10 year does.
The best line in today’s coverage came from Bankrate’s Jeff Ostrowski: when the Fed raised a quarter point last month, mortgage rates jumped three quarters of a point in a month. Mortgage rates follow the 10 year Treasury, not the overnight rate.
That is the variable to watch. Bond investors have been pricing inflation risk off rising oil prices tied to the war with Iran. If oil cools, the 10 year can come in even while the Fed is hiking. If it doesn’t, a pause today does nothing for your borrowing cost.
The trend line
Since late February, the 30 year fixed has gone from under 6% to above 7.3%. That is more than a full point in about eight months, and it lands directly on affordability for buyers and on exit assumptions for anyone holding a deal.
Realtor.com’s chief economist Danielle Hale put it plainly: rates have not come back to their mid September level, and the housing market is feeling it.
What it means for investors
1. Stop underwriting a refinance. If a deal only works when rates fall back under 6%, it is a bet, not an investment. Underwrite at today’s rate and stress it higher.
2. Fix or cap floating rate debt. Two more hikes are priced. Anything floating without a cap is exposed to the part of the curve the Fed controls directly.
3. Higher rates thin the buyer pool. Leveraged buyers step back when debt costs this much. That leaves better pricing for cash and patient equity, and it surfaces sellers who need to transact, especially in land and stalled projects.
4. Rental demand holds. With mortgages above 7%, would be buyers rent longer. Workforce rentals near real job centers stay full.
What it means for developers
1. Construction carry is tied to short rates. Construction loans price off SOFR and prime, which move with fed funds. Today buys you about six weeks. December is the next test.
2. For sale product has to get smaller and sharper. Buyers are qualifying at 7% plus. Rate buydowns are getting more expensive. Attainable, right sized product near employment is where absorption is.
3. The margin is in the land basis. In many markets, land sellers still haven’t repriced to a 7% world. That gap is closing. Buying land at the right basis, entitling it, and being ready when the cycle turns is how you win this stretch.
4. Equity over leverage. In this rate environment, the capital stack is the strategy. Less debt, more control, and terms that survive a December hike.
What to watch next
-
The midterm elections next week
-
The next inflation prints heading into December
-
The December FOMC meeting
-
Oil and the 10 year Treasury yield
-
Freddie Mac’s weekly mortgage rate survey every Thursday
The bottom line
The pause is a breath, not a turn. Price your deals for the rate you have, buy basis instead of hope, and let the people who need rates to fall be your sellers.
If you are tracking land and housing fundamentals market by market, that is exactly what we built LandBriefing for. And if you want a second set of eyes on a deal in this rate environment, reach out through Kaufman Real Estate & Consulting.
Source: Keith Griffith, “Fed Pauses Interest Rate Hikes for Now as Key Midterm Elections Loom,” Realtor.com, October 28, 2026. Mortgage rate data from Freddie Mac. Developing story.
About the Author
Daniel Kaufman is the founder and CEO of Kaufman & Company, a private investment and holding firm working across real estate development, venture investment, and infrastructure. He writes The Kaufman Report on housing, land, and capital markets from an operator’s seat.
Daniel@kaufmanredev.com | danielkaufmanre.com